Could Twitter Force Elon Musk to Buy Twitter?
Armchair lawyers claim the court could order Elon Musk to go through with his offer to buy Twitter for $54.20 a share under a remedy known as 'specific performance'. Is this true? [updated]
By Alexander Muse ·

Since Elon Musk put his deal to buy Twitter on hold1 I have repeatedly heard people claim that the Delaware Chancery Courts could force the billionaire to close on the deal. For example, a 30-year lawyer named Steven Ellison, Esq. wrote an article in FindLaw asking that very question suggesting, “If Musk tries to abandon the deal, Twitter could sue him and ask for specific performance. This remedy is usually hard to get, but Musk agreed to a powerful specific performance clause in the merger agreement. In fact, he didn't just agree that Twitter could get specific performance. He promised that he wouldn't argue it couldn't.”2 Shanthi Rexaline from Benzinga wrote, “Musk may now be left with no option but to complete the transaction at the $44 billion or $54.20-per-share price he committed to at the time of the agreement.”3 But are they right? Could a court force Elon Musk to personally buy Twitter if he doesn’t want to buy it? The answer is NO.
Over the past couple of months, I have written about Elon Musk’s deal to purchase Twitter. My first post asked the question, “Can Elon Musk Save Democracy? The billionaire wants to resurrect Twitter's founding principle of free speech.”4 My next post wondered if “Elon Musk was Paying Too Much for Twitter. Will Twitter's Board Agree to a More Reasonable Price?”5 Then I predicted that “Elon Won't Pay $1 Billion Breakup Fee. The only question left for Twitter to answer what does the company know about its Bot problem and when did it know it. The future of the company hangs in the balance.”6 The company then released a day-by-day chronology of the deal I shared in a post titled, “Elon Musk + Twitter: Chronological Timeline of Events Prior to the Execution of the Buyout. The company reveals significant cooperation between Jack Dorsey and Elon Musk.”7 I even made memes about the bots. I then made the bold prediction that “UPDATE: Elon Musk Isn't Buying Twitter. The updated story behind the billionaire's apparent decision to leave the social network at the altar. Insiders believe there is almost ZERO chance this deal will close.”8
To better understand the deal it might be helpful to understand who exactly is buying Twitter. I put together this diagram to help explain the nature of the transaction - a reverse triangular merger:
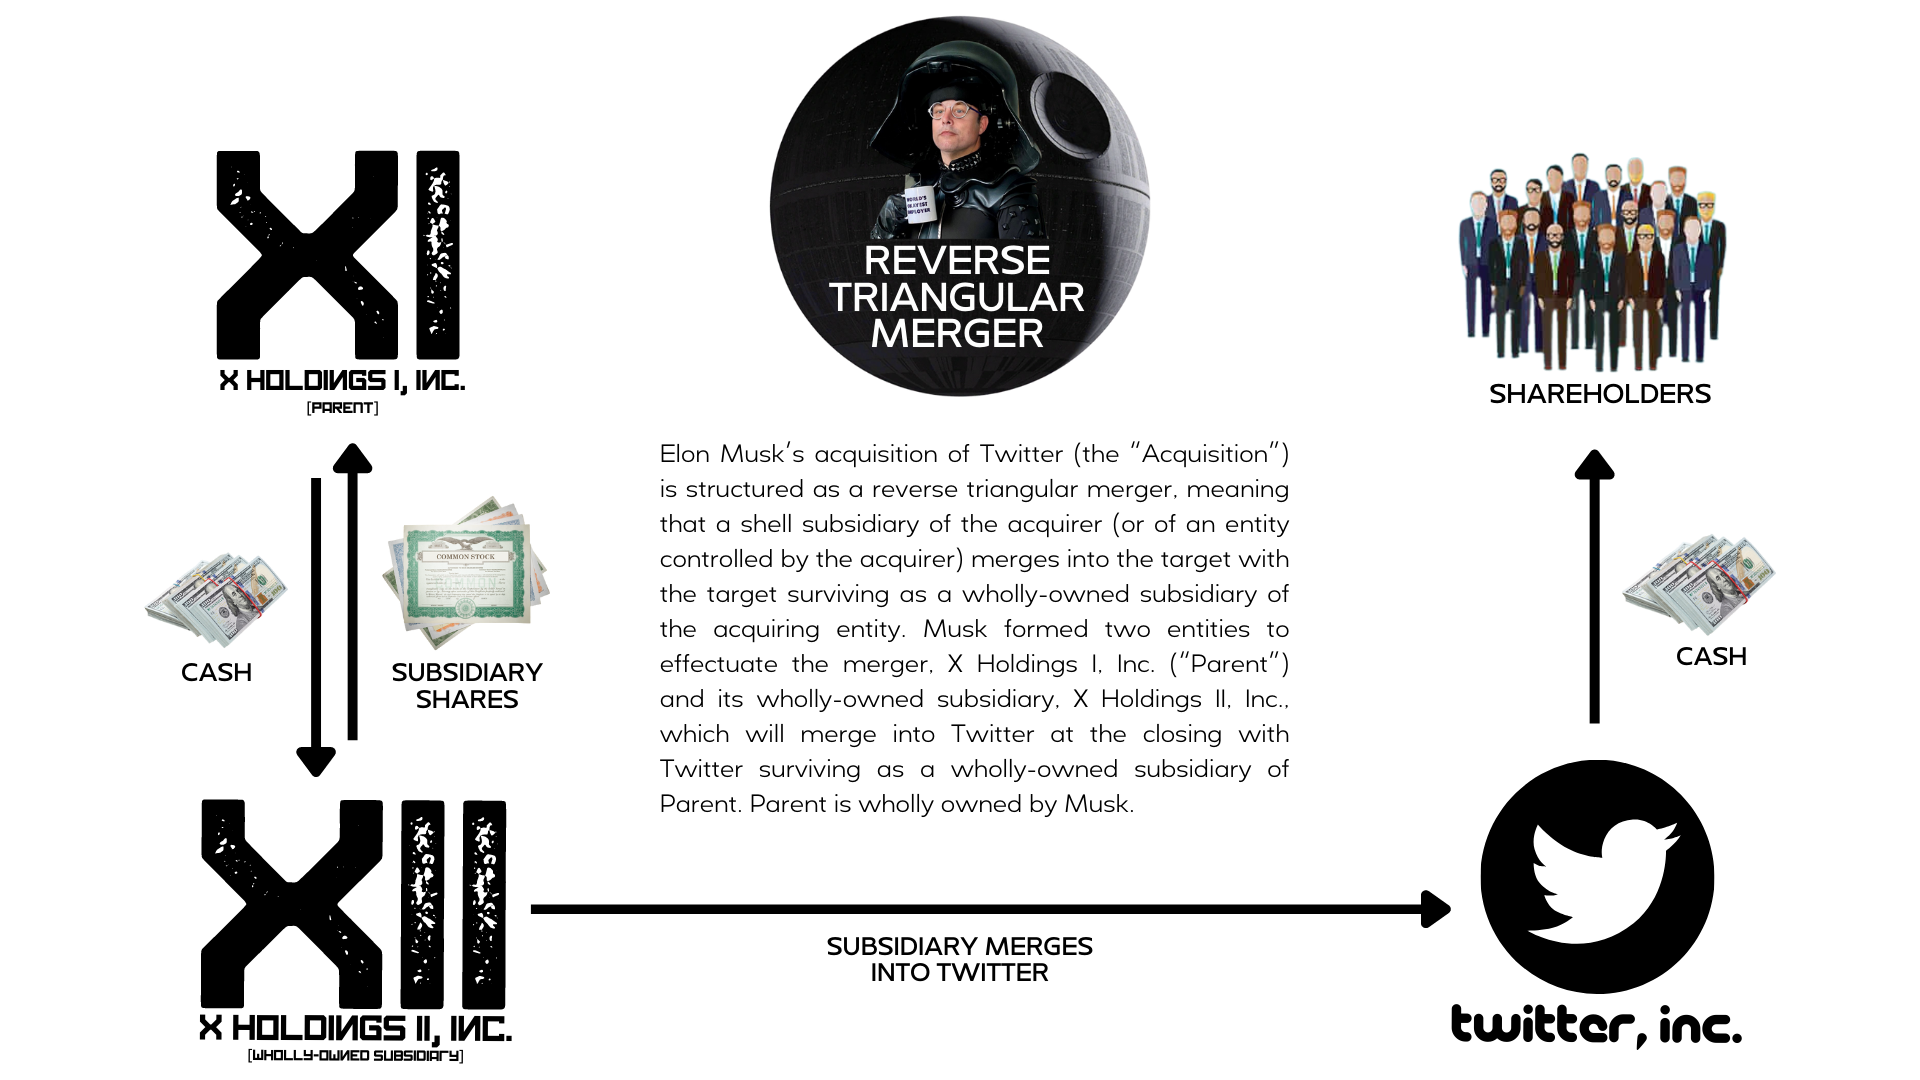
Based on the Merger Agreement, the billionaire known as Elon Musk is not actually buying Twitter. In fact, the eventual owner (if the deal goes through) would be X Holdings I, Inc. which is presently controlled by Elon Musk. Currently, the entity only has a few assets including the actual Merger Agreement with Twitter, a ‘parent guarantee’ for part of the breakup fee (>$1B)9, and an “Equity Financing Commitment” from Elon Musk (discussed below). If a Delaware Chancery Court forced X Holdings I, Inc. to buy Twitter it would be unable to do so as it lacks the capital to fund the transaction - but there is more to the story.
Recognizing this, Twitter asked Musk to provide a personal guarantee to X Holdings I in some amount less than the $1B reverse breakup fee.10 The Merger Agreement references the ‘Parent Guarantee’ in Section 5.10:
Section 5.10 Parent Guarantee: Parent has furnished the Company with a true, complete and correct copy of the Parent Guarantee. The Parent Guarantee is in full force and effect and has not been amended, modified or terminated. The Parent Guarantee is a (i) legal, valid and binding obligation of the Guarantor and of each of the parties thereto and (ii) enforceable in accordance with its respective terms against the Guarantor and each of the other parties thereto. There is no default under the Parent Guarantee by the Guarantor, and no event has occurred that with the lapse of time or the giving of notice or both would constitute a default thereunder by the Guarantor.
In conjunction with the Merger Agreement, Elon Musk delivered X Holdings I (the “Parent”) an “Equity Financing Commitment” letter11 that defined Elon Musk or his assigns as the “Equity Investor”. In the letter, the “Equity Investor” agreed to provide the equity portion of the purchase price - $33.5 billion of $44 billion “Aggregate Equity Commitment” - to the Parent under certain conditions.
In my review of the letter several of the conditions included by Musk convince me that there is no realistic way, the court could force Elon Musk to provide $33.5 billion in cash to the Parent.
If Elon Musk announced he did not want to buy Twitter, the Debt Financing contemplated by the Debt Commitment Letters would immediately terminate. There isn’t a bank on the planet that would lend $10.5 billion to the Parent if Elon Musk wasn’t interested in buying Twitter. And the agreement makes it clear the banks have NO obligation to any of the parties. Under the terms of the Equity Financing Commitment letter, the Equity Investor (aka Elon Musk) does not have ANY obligation to fund any amount over $33.5 billion as outlined in Section 1(b):
“Notwithstanding anything else to the contrary in this letter agreement, the Equity Investor (together with his assigns) shall not have any obligation under any circumstances to contribute to, or otherwise provide to, Parent, directly or indirectly, funds in an amount in excess of the Aggregate Equity Commitment…”
Furthermore, even if Twitter would agree to lower the price to $33.5 billion to ‘force’ Musk to fund the deal without the additional debt, the terms of the Equity Financing Commitment letter release the Equity Investor from its obligation in the event that the Debt Financing is not provided in Section 1(b)(iii):
“substantially contemporaneous receipt by Parent or Acquisition Sub of the cash proceeds of the Debt Financing contemplated by the Debt Commitment Letters in accordance with the terms and conditions of such Debt Commitment Letters or any Alternative Financing that Parent accepts from alternative sources pursuant to Section 6.10(c) of the Merger Agreement (subject only to the funding of the Aggregate Equity Commitment contemplated by this letter agreement).”
Twitter’s DEFA14A further clarifies:
“The Merger Agreement also provides that Twitter, on one hand, or Parent and Acquisition Sub, on the other hand, may specifically enforce the obligations under the Merger Agreement, except that Twitter may only cause Mr. Musk’s equity financing commitment to be funded in circumstances where the conditions to Parent’s and Acquisition Sub’s obligations to consummate the Merger are satisfied and the debt and margin loan financing is funded or available. As described above, if the conditions to Parent’s and Acquisition Sub’s obligations to complete the Merger are satisfied and Parent fails to consummate the Merger as required pursuant to the Merger Agreement, including because the equity, debt and/or margin loan financing is not funded, Parent will be required to pay Twitter a termination fee of $1.0 billion.”
To conclude, if Elon Musk decides not to move forward with the deal the Delaware Chancery Court could not use specific performance to force the billionaire to buy the company UNLESS the banks that agreed to provide X Holdings I, Inc. $10.5 billion in debt (secured by Elon’s personal wealth) and actually fund the deal sending the Parent the money. The court could NOT force the banks to lend money to X Holdings I, Inc. and there is ZERO chance that they would do so if Elon Musk didn’t want to do the deal. So technically, the folks that suggest Elon could be forced to buy Twitter are correct - but in reality, they are most certainly wrong. The deal is not going through under the terms contemplated in the Merger Agreement unless Elon wants it to go through, period.
UPDATE: My friends on Reddit argue that the banks would fund the transaction even if Elon Musk didn’t want to do the deal. Here was my response:
First, the banks that agreed to provide the Parent with funding have very easy outs. In fact, under the terms of the bank loans Elon must agree to provide additional collateral if the value of his collateral declines. If he refuses, the commitments made by the banks are null and void. Given this fact it is important to remember that neither Elon Musk nor the banks are party to the Merger Agreement. Elon's Equity Commitment Letter is with the Parent (not Twitter). Elon Musk owes no duty to Twitter. The bank's debt commitment letters are with the Parent as well. They owe no duty to Twitter.
The easiest out for the banks comes in the form of needed approvals from their credit committees before closing. In the event that market conditions deteriorate impacting the value of the collateral (i.e. Twitter itself and Elon's Telsa stock), the committee would have an obligation to deny funding. If the sponsor of the Parent stated that he did not want to do the deal, the committee would be negligent to fund the debt. They certainly wouldn't suffer a negative impact on their credibility.
But let's assume you're right. Elon Musk refuses to do the deal. Twitter sues the Parent and Musk for specific performance. The banks testify that they WILL fund the debt despite Musk's refusal and the litigation. The Equity Financing Commitment letter contemplates this by releasing Elon Musk from his commitment in the event of litigation in Section 2:
The Equity Investor’s obligation to fund the Aggregate Equity Commitment will terminate automatically and immediately upon the earliest to occur of (a) the institution or assertion of any action, suit, claim, arbitration, or other proceedings, whether at law, in equity or otherwise (a “Claim”), by the Company or its controlled Affiliates against any of the Equity Investor or any Related Party (as defined below) arising under, or in connection with, this letter agreement, the Limited Guarantee, the Merger Agreement
There is literally no way the court could force Elon to buy the company if he doesn't want to...
THE FILINGS
INITIAL PLEADINGS
PRIMARY SOURCE DOCUMENTS
CASE SCHEDULING ORDER
CONFIDENTIALITY ORDER
MOTION TO EXPEDITE
3rd PARTY SUBPOENAS
…coming soon
https://www.findlaw.com/legalblogs/courtside/is-elon-musk-going-to-buy-twitter-or-not/
https://www.benzinga.com/m-a/22/05/27294767/how-the-tables-have-turned-lawyers-say-elon-musk-could-be-forced-to-buy-twitter

https://www.sec.gov/Archives/edgar/data/0001494730/000110465922050686/tm2213741d1_ex99-l.htm
https://www.sec.gov/Archives/edgar/data/0001494730/000110465922050686/tm2213741d1_ex99-l.htm
https://www.sec.gov/Archives/edgar/data/1418091/000110465922064655/tm2216931d1_ex-n.htm